We tend to file disasters in separate drawers. Fire is a West Coast problem. Flood is a coastal problem. Different seasons, different maps, different agencies, different insurance.
The hold up: our agencies, budgets and insurance are split by hazard. The land isn’t.
On the ground, these hazards overlap.
What a fire does to the next storm
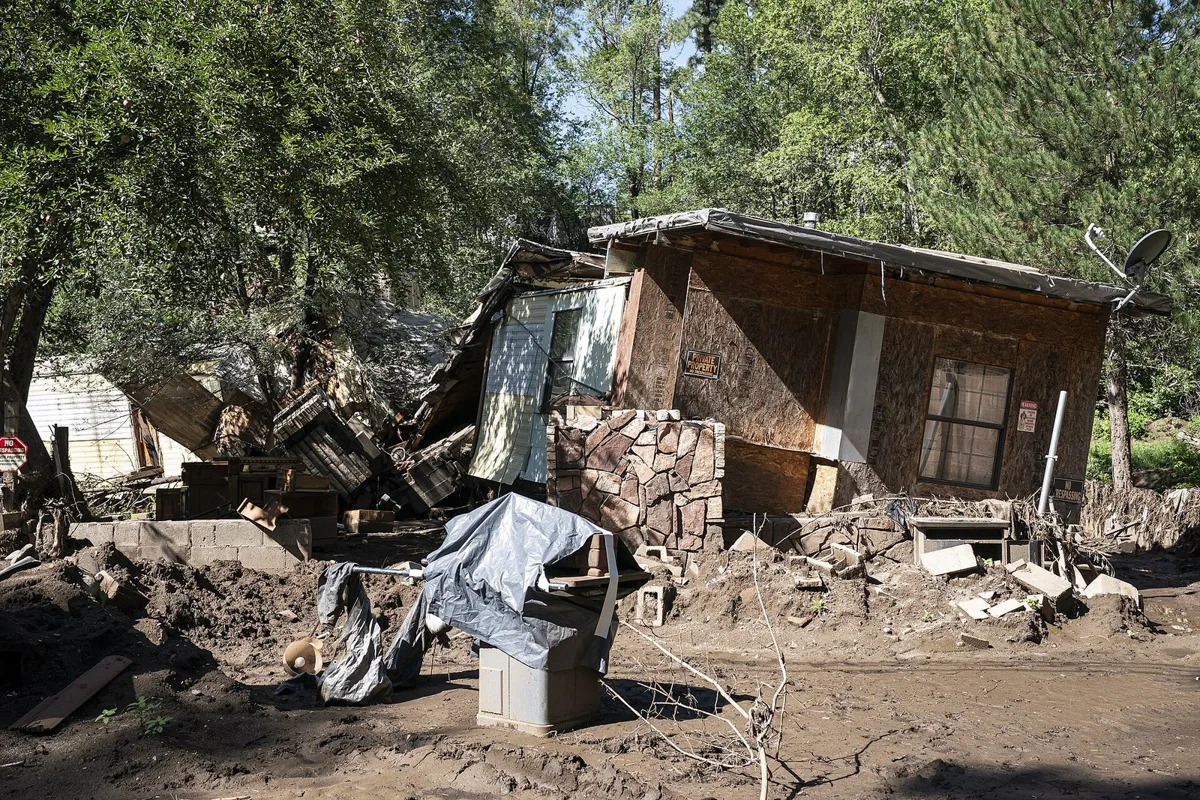
When a wildfire burns hot enough, it bakes the soil into something close to a hard surface. The plants and roots that used to catch rain are gone. So the next storm does not soak in. It runs off, fast, carrying ash, mud, rocks and sometimes whole trees down the slope.
The US Geological Survey has found that in Southern California, as little as 0.3 inches of rain in 30 minutes has triggered debris flows on burned slopes. That is an ordinary afternoon shower. The risk can last for years after the smoke clears.
Two hazards, two sets of paperwork
Here is where it gets strange. A standard homeowners policy usually covers fire. It usually does not cover flood or mudflow. For that you need a separate flood policy, and new flood policies normally take 30 days to kick in.
There is an exception. If the flooding comes from a wildfire on federal land, and you buy a policy within 60 days of the fire being contained, the wait can be waived. If the fire burned on state or private land, the normal wait usually applies.
Think about that from the point of view of a family watching the hillside above their home. How fast they can be protected depends partly on who owned the land that burned. The water coming down the slope is the same either way.
Almost nobody connects this: who owned the land that burned decides how fast a family can get covered.
How building codes get updated
Building codes are one of the quietest and most powerful tools we have. They decide how a roof holds in wind, how high a home sits above water, what a wall is made of. They are also updated slowly, and adopting the latest version is up to each state or town.
FEMA tracks how many places have adopted current codes that resist natural hazards. As of this quarter, it is 35 percent of the places that face these hazards, covering about half the population. And the hazards on that tracker are wind, hurricanes, tornadoes, floods and earthquakes. Wildfire and heat are not on the list.
Energy codes help in emergencies too
We usually think of energy codes as being about saving money on bills. But a home that is well sealed and well insulated also keeps wildfire smoke out, stays cool longer when the power goes out in a heat wave, and stays warm longer in a winter storm. That extra time can keep people safe until the power or help comes back.
Who gets to raise the bar varies more than you would expect. In New Jersey, for example, the building code is set statewide, so a town that wants stronger energy standards than the state has no simple way to adopt them on its own.
The new equipment brings its own fire risk
Solar panels, electric cars and home batteries are how a lot of places are cutting emissions and keeping the lights on during outages. They are worth building. They also pack a lot of energy into a small space, and a lithium-ion battery that fails can burn hot, long and hard to put out.
Fire and flood meet here too. After Hurricane Ian in 2022, 36 electric vehicles in Florida caught fire after being soaked in saltwater, according to federal safety regulators. Some burned days or weeks later, and some took homes that had survived the storm itself with them.
Big batteries raise the same question at a bigger scale. In January 2025, a fire at the Moss Landing battery storage plant in California forced about 1,200 people to evacuate. On 18 September 2026, a new fire at the same site put nearby residents under a shelter in place order.
The good news is that rules work when they match the equipment. In New York City, deaths from lithium-ion battery fires fell from 18 in 2023 to one in 2025 after the city wrote battery safety standards into law. The codes, the siting and the firefighting plans need to grow up alongside the clean equipment.
Lives, property and property taxes
Each of these risks usually gets discussed in one currency at a time. Emergency managers, insurers and budget offices each look at one of these, lives, property or taxes, even though it is the same event.

Follow the money x disaster data. Who is responsible?
And the three are tied together in a loop most people never see. Towns pay for fire departments, schools and storm drains largely through property taxes. When homes burn or flood, their value drops, and so does the money that pays for the firefighters and the pumps.
At Rebuild by Design, our NJ Flood Risk = Financial Risk analysis found that homes and buildings at risk of flooding in New Jersey already bring in $3.2 billion a year in property taxes. By 2050, nearly $6 billion a year could be at risk. Those taxes also pay for the services that keep everyone else safe.
So when a town weighs a new battery site, new homes on a burned slope or a new floodwall, the conversation needs all three on the table at once: who could get hurt, what could be lost, and what happens to the budget that protects everyone else.
One place, not one hazard
Every rule in this story made sense when it was written. Each one was built for a single kind of disaster.
The question for this decade is what it would look like to plan for places instead of for hazards. Planners have a name for this: multi-hazard planning. It sits at the center of adaptation. A hillside that burns in August and slides in January is one place with one set of neighbors.
The future I want to work toward: planning for places, not one disaster at a time.